Buying a Manufactured Home in Northern New Mexico
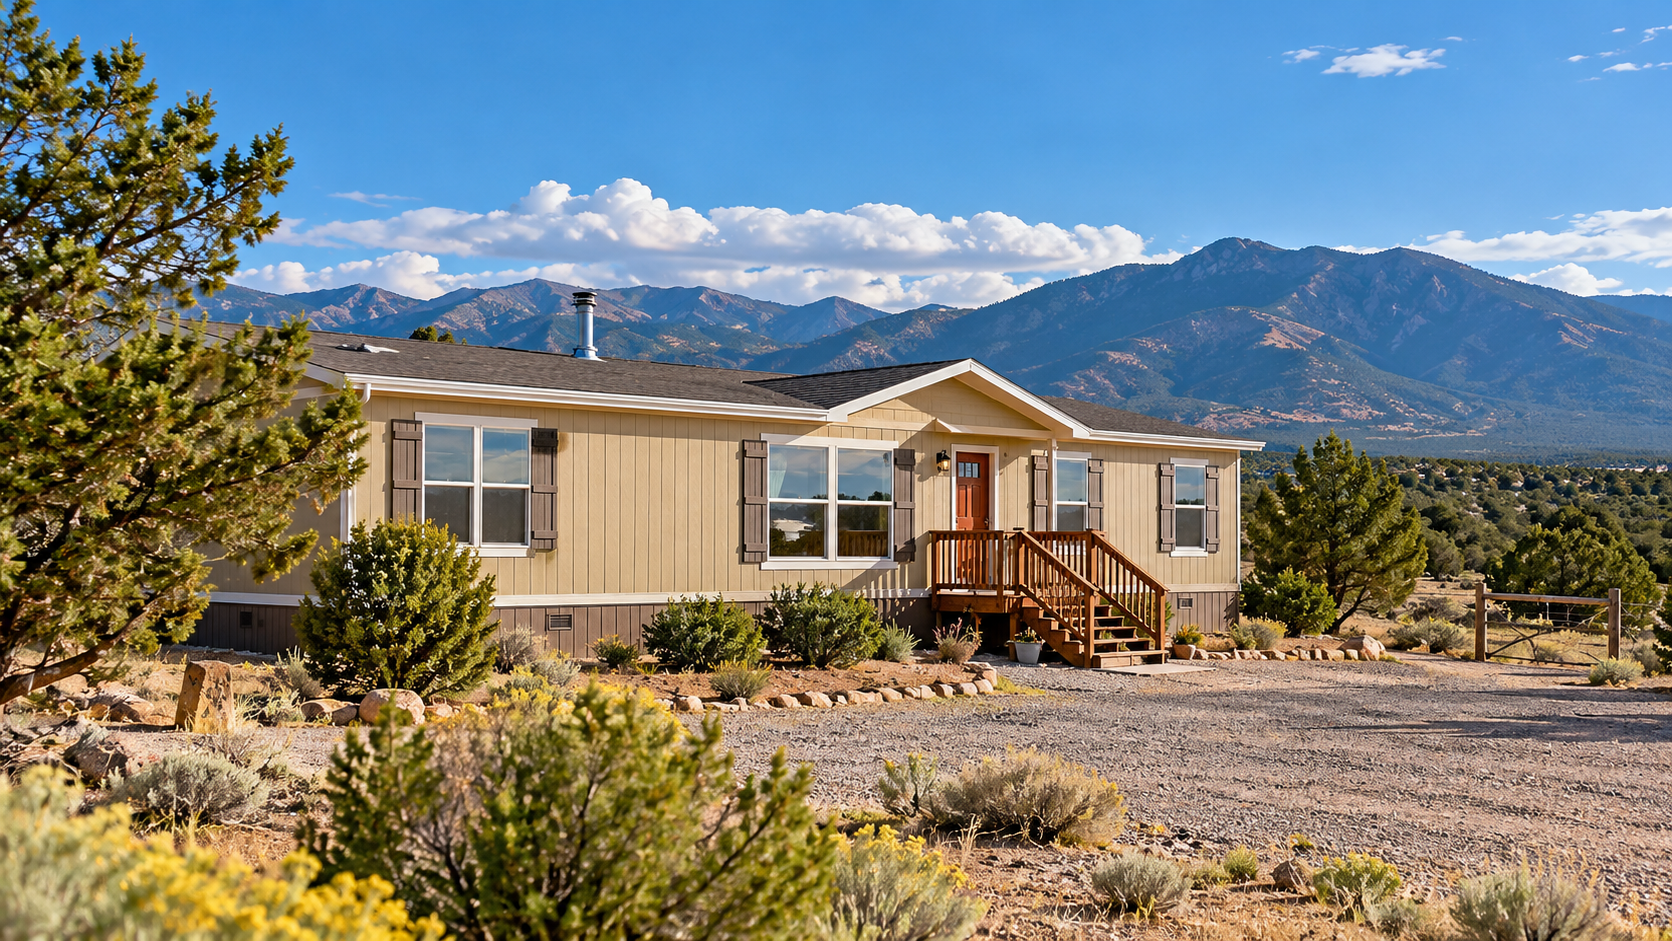
What Buyers Need to Know
Manufactured homes can be a great option in Northern New Mexico, especially for buyers looking for affordability, more land, or a little more space outside of town.But they can also come with a few extra questions that don't always come up when buying a traditional site-built home.I've worked with manufactured-home properties where the home itself wasn't necessarily the issue. Instead, questions involving financing, title, the foundation, septic system, or the land became the bigger concern.That doesn't mean you should avoid manufactured homes. It just means there are a few things worth figuring out early—preferably before you've fallen in love with the property.Can You Finance a Manufactured Home in New Mexico?
Yes, many manufactured homes can be financed. Depending on the property and buyer, financing may be available through conventional, FHA, VA, or other loan programs.
However, not every manufactured home will qualify.
The home's age, foundation, title status, condition, installation, and whether it has ever been moved can all potentially affect financing. The land and other property conditions can matter too.
If you're considering a manufactured home, one of the best things you can do is talk with a lender who has experience financing manufactured homes in New Mexico. A preapproval for a traditional home doesn't necessarily mean every manufactured home will qualify under the same loan.
What About the Title?
Manufactured homes can have a more complicated title history than traditional homes because the home and the land may not always have started out as one piece of real estate.
Before purchasing, it's important to understand what you're actually buying and how both the home and land are documented.
If records are missing, inconsistent, or don't match the home sitting on the property, that can potentially affect financing, title insurance, and a future sale.
These are issues I'd much rather uncover at the beginning of a transaction than a few days before closing.
Does the Foundation Matter?
Absolutely—especially if you're financing the purchase.
Depending on the home and loan program, a lender may have specific foundation requirements or require additional inspections or certifications.
A home having sat in the same place for 20 years doesn't automatically mean its foundation will meet the requirements of a particular loan.
This is another reason I like getting the lender involved early.
Has the Manufactured Home Ever Been Moved?
This is an easy question to overlook, but it's an important one.
A manufactured home's relocation history can affect eligibility for certain types of financing. If the home was originally installed somewhere else and later moved to its current location, your lender needs to know.
If nobody knows the answer, we may need to do some additional homework.
Don't Forget About the Property Around the Home
This is especially important when looking at manufactured homes on acreage or rural property in Santa Fe County or Rio Arriba County.
Where does the water come from? Is there a private well or community water system? What kind of septic system serves the property? Does the property have documented legal access?
You can have a perfectly good manufactured home and still run into an issue with the land, well, septic system, easement, or access.
That's why I look at the whole property—not just the house sitting on it.
If you're buying rural property, you may also want to read my guide on what it means when a property doesn't have a recorded easement.
What About Porches, Garages and Additions?
Older manufactured homes often have improvements that were added over the years: porches, decks, garages, carports, room additions, or roof structures.
Those additions aren't automatically a problem.
But we do want to understand what was added and whether it creates any questions involving permits, inspections, appraisal, insurance, or financing.
Again, the goal is simply to find these things before they become surprises.
Why Does the Listing Say “Cash Only”?
Whenever I see a manufactured home listed as cash only, I want to know why.
Maybe it's the age of the home. Maybe it's been moved. Maybe there's a foundation or title issue. Or perhaps the problem isn't the home at all—it could involve the septic system, access, land, or something else entirely.
Cash buyers should ask the same questions.
Even if you don't need financing today, consider what happens when you eventually sell. If there's an issue preventing buyers from financing the property now, could that same issue limit your future buyer pool?
That's a much more important question than simply asking whether you can afford to pay cash.
Are Manufactured Homes a Good Option in Northern New Mexico?
They absolutely can be.
For some buyers, a manufactured home can provide more space, more land, or a more affordable path to homeownership than other options available in Northern New Mexico.
You just need to know what you're buying.
I like to think about these properties as four pieces:
The home. The land. The title. The financing.
If all four make sense, great. If one doesn't, it's better to find out while you still have options.
Buying a Manufactured Home in Northern New Mexico?
I work with buyers and sellers throughout Los Alamos, Santa Fe, and Rio Arriba Counties, including Los Alamos, White Rock, Española, Pojoaque Valley, Santa Fe, Chimayó, and surrounding Northern New Mexico communities.
If you're considering a manufactured home or rural property, I can help you identify the questions that need to be answered and work with your lender, title company, inspectors, and other professionals to help you understand what you're buying.
Danika Wright
Associate Broker | Realty One of New Mexico
Serving Los Alamos, Santa Fe & Rio Arriba Counties
This article is for general informational purposes and is not legal, lending, engineering, title, tax, or inspection advice. Requirements vary by property and loan program, so buyers should consult the appropriate professionals regarding their specific transaction.